


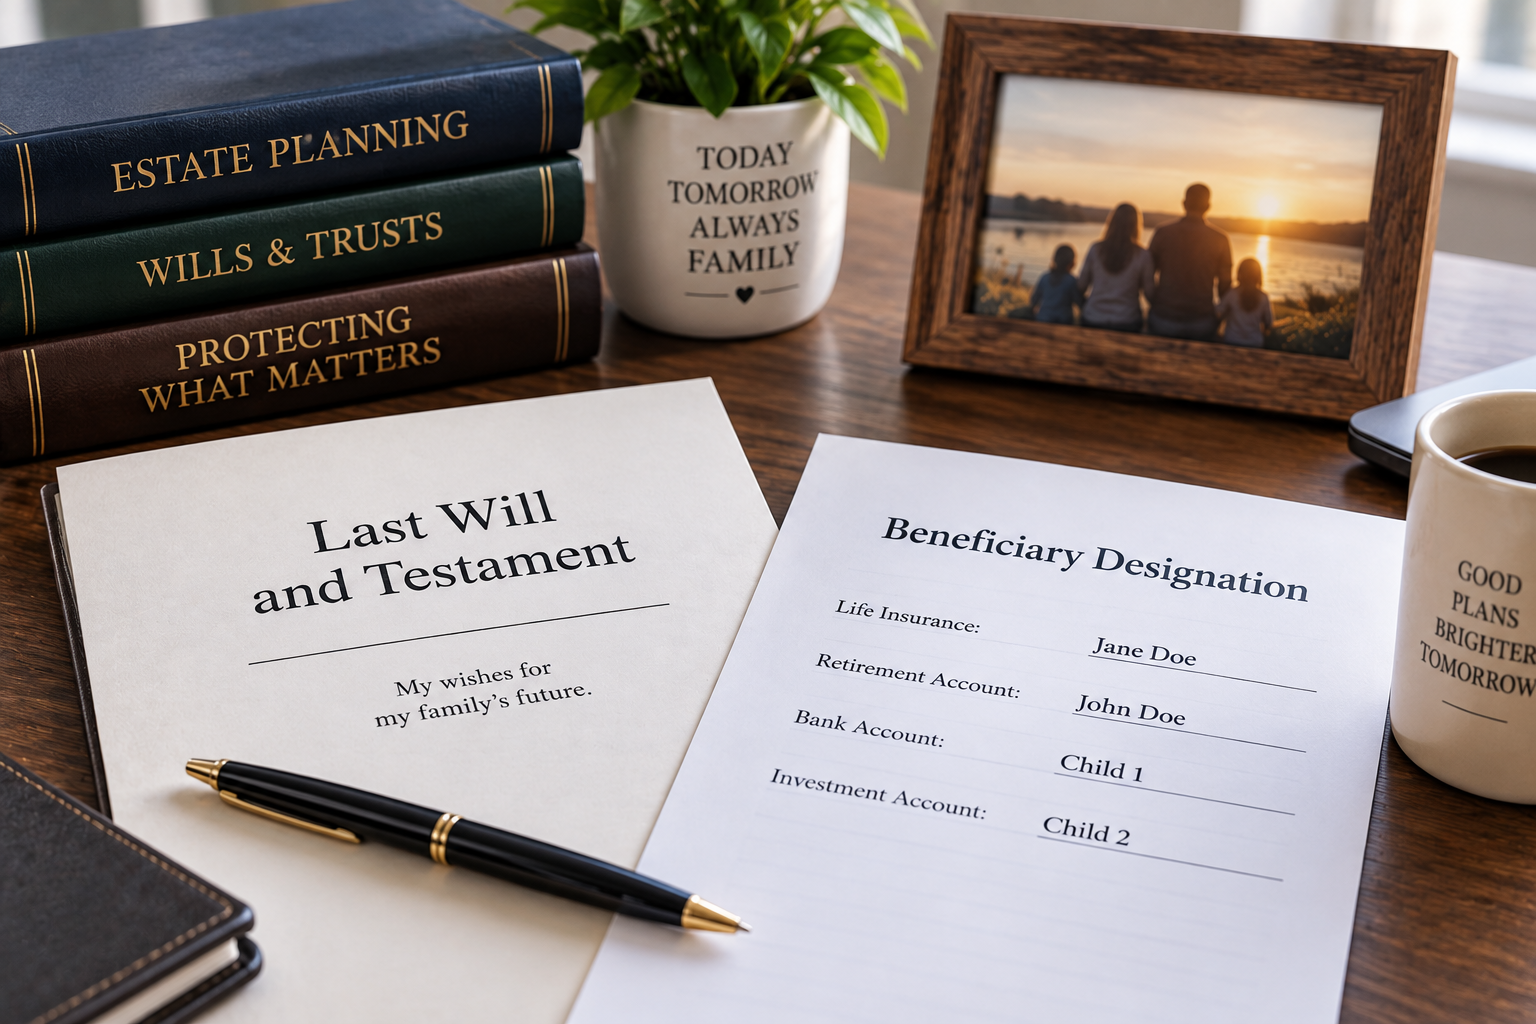

Your Will Says One Thing. Your Beneficiary Form Says Another. Which One Wins?
You updated your will years ago.
It clearly says who should receive your property when you die. You assume everything is handled exactly the way you want.
But there is one problem.
Your life insurance policy still names your former spouse. Your retirement account names only one of your children. Or a bank account has a beneficiary designation you filled out so long ago that you barely remember doing it.
When your will and your beneficiary forms say different things, your will may not control where that money goes.
Your Will Does Not Control Everything You Own
A will is an important estate planning document, but it does not necessarily determine who receives every asset after your death.
Certain assets can pass directly to a named beneficiary.
Common examples may include life insurance policies, retirement accounts, and accounts with payable on death or transfer on death designations.
When a valid beneficiary designation exists, the asset generally passes according to that designation rather than the instructions in your will.
That can create a very different result from what you intended.
Beatriz Figueroa
Mark was able to assist my family and I on a will & trust. We were educated regarding the topic and that’s thanks to Mark and his amazing team. I cannot recommend them highly enough.
Imagine You Changed Your Will but Forgot One Form
Consider a parent with two adult children.
Years ago, the parent named the older child as the beneficiary of a retirement account. Later, the parent creates a will stating that the estate should be divided equally between both children.
The parent assumes both children will receive equal shares of everything.
But if the retirement account still names only the older child as beneficiary, that account may pass directly to the older child outside of the will.
The remaining estate may still be divided according to the will.
The end result could be far from equal.
An Old Beneficiary Can Create an Unwanted Surprise
Beneficiary forms are easy to forget because they are often completed when an account or policy is first opened.
Years pass.
People get married. They get divorced. Children are born. Relationships change. Beneficiaries die. Financial circumstances change.
Your will might be updated after one of those major events while your retirement account or life insurance policy still contains information from an earlier chapter of your life.
That is why reviewing the will alone may not be enough.
Divorce Makes Beneficiary Planning Especially Important
After a divorce, many people immediately think about changing their will.
But beneficiary designations deserve attention too.
Different types of assets can be governed by different rules, and divorce may affect beneficiary rights in ways that depend on the account, policy, and applicable law.
Instead of assuming an old designation has automatically disappeared, review each account and confirm that the beneficiary information reflects your current wishes.
What Happens If the Beneficiary Dies Before You?
Another potential problem arises when the person named on an account dies first.
What happens next can depend on the terms of the account or policy and whether you named a contingent beneficiary.
Without an appropriate backup beneficiary, the asset may be distributed according to the governing documents or applicable rules rather than exactly as you expected.
This is one reason contingent beneficiaries can be an important part of an estate plan.
Your Estate Plan Should Work as One Plan
Estate planning should not be treated as a collection of unrelated documents.
Your will may say one thing.
Your trust may say another.
Your retirement accounts and life insurance policies may have their own beneficiary designations.
Bank and investment accounts may have additional instructions.
The goal is to make sure those pieces work together.
Otherwise, you can have a carefully drafted will that still produces an unintended result because an old beneficiary form was never changed.
When Should You Review Your Beneficiaries?
You do not need to wait until something goes wrong.
A beneficiary review is particularly important after major life events such as marriage, divorce, the birth or adoption of a child, the death of a beneficiary, a significant change in finances, or the creation of a new estate plan.
It can also be helpful to periodically review your accounts even when nothing major has changed.
You may discover a designation you forgot existed.
Do Not Assume Your Will Gets the Final Word
A will can be central to your estate plan without controlling every asset you own.
That is why a complete estate plan should consider not only what your will says, but also how your accounts, policies, trusts, property ownership, and beneficiary designations fit together.
At MontanaroLaw, we help New York individuals and families create and review estate plans that reflect their wishes. If you are unsure whether your will and beneficiary designations work together, contact us today to review your estate plan and help make sure your assets are positioned to pass the way you intend.
